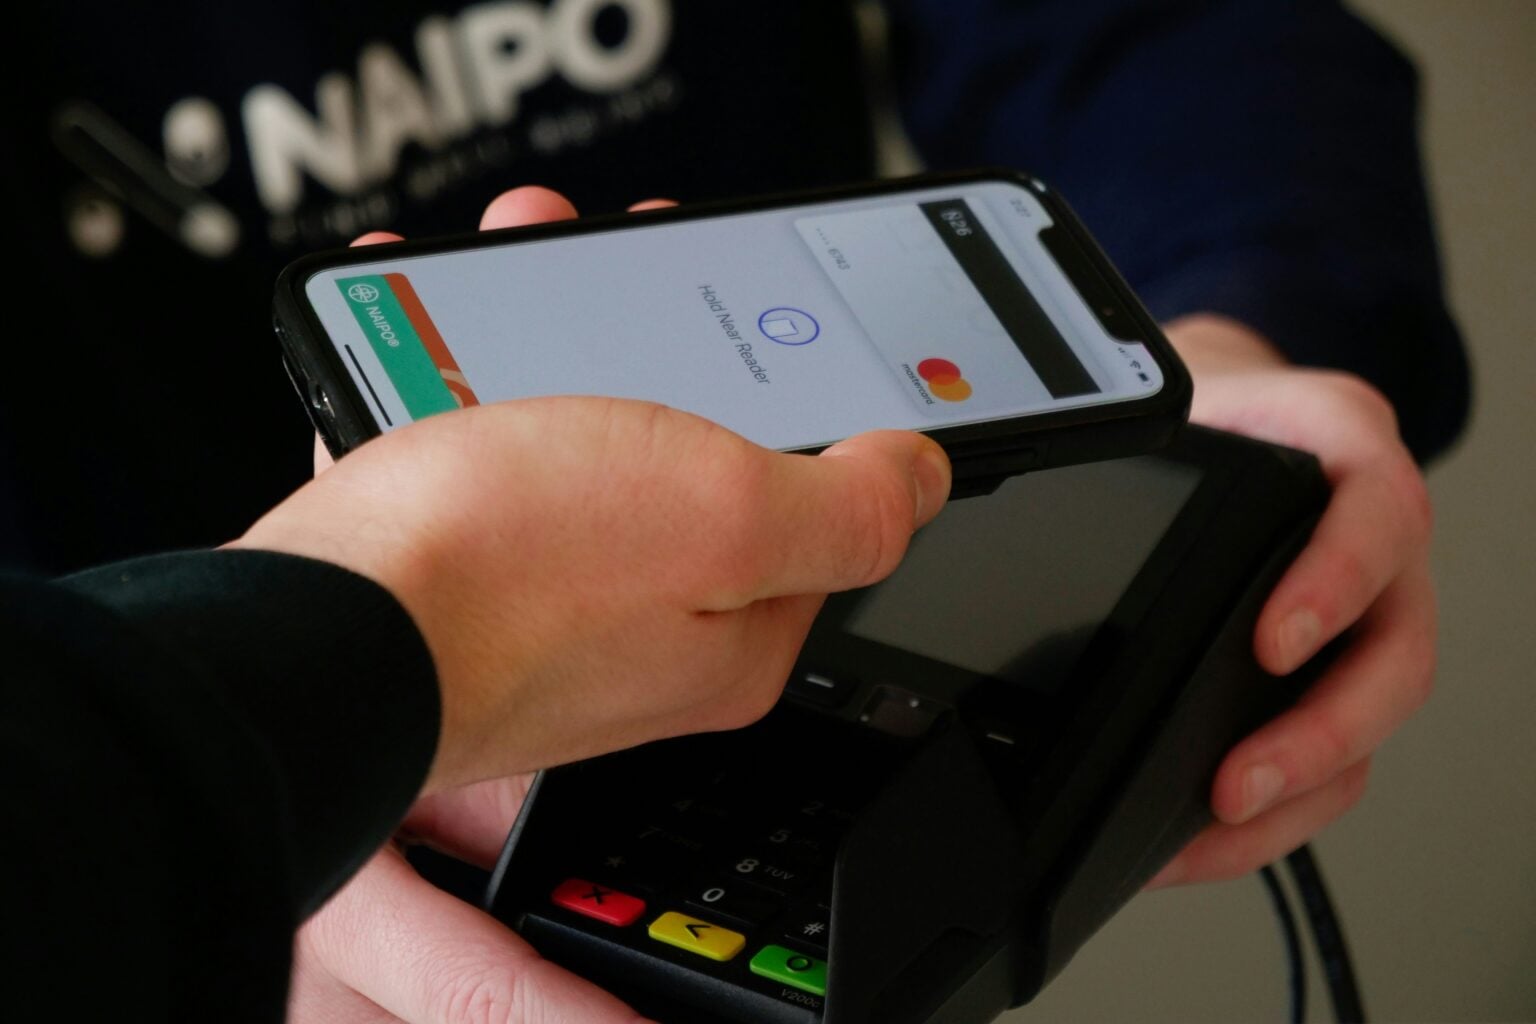
Self-employed workers in Spain are being urged to keep clear records of personal Bizum payments to avoid disputes with the taxman over whether the money came from their business.
Payments from friends to split a meal or cover shared holiday costs are not business earnings.
But mixing private transfers with customer payments can make it harder to explain incoming money during a tax inspection.
Monica Serra Garcia, a tax expert at Declarando, warned that unexplained receipts could end up being treated as business income if the recipient cannot demonstrate their origin.
Her advice comes as Spain strengthens its reporting requirements for banks and payment providers.
Since January 2026, financial institutions have been required to report professional card and mobile-linked payments monthly through Modelo 170, without a minimum reporting threshold.
The obligation to submit that form falls on the financial institutions.
Personal Bizums between individuals are explicitly excluded from this reporting requirement, according to the Tax Agency.
Being registered as self-employed does not automatically turn a reimbursement from a friend into taxable business income.
However, speaking to business publication Diario AyE, Serra recommends keeping business and personal banking separate to make any future checks easier.
Although a separate business account is not generally compulsory for an individual sole trader, she advises using one account and, where possible, a dedicated Bizum service, for professional payments.
Those using a single account should give transfers clear descriptions and retain supporting evidence.
For shared expenses, that could mean keeping the restaurant receipt or holiday booking alongside a record of each person’s contribution. Family loans should be documented with an agreement.
Serra also recommends regularly comparing bank receipts with invoices and accounting records.
Differences do not necessarily indicate undeclared earnings: VAT, tax withheld by clients, delayed payments, refunds and platform fees can all explain discrepancies.
But genuinely undeclared business receipts may lead to additional tax, interest and, depending on the circumstances, penalties.
Serra expects the impact of the expanded reporting to become more apparent when taxpayers submit their 2026 income tax returns in spring 2027.